


Enjoy your new home sooner with our Bridging Loan


Bridging Loan
-
 Borrow up to 80% LVR
-
Bridging period up to 12 months
-
No monthly or ongoing fees
Buying your next home has never been easier. Chat through the process of securing a bridging loan with our Australian-based home lending specialists who’ll provide you with personal support when you need it.
Whether you’re upsizing or downsizing, let us give you the peace of mind knowing that you can be in your new home while waiting to sell your current home at the right time. Our bridging loan is interest-free during the first three months.
You’ll benefit from the best outcome while the sale funds from your previous property goes toward your bridging loan. Once you’ve completed the bridging period, enjoy the flexibility of an offset sub-account which can potentially speed up your repayments, and the ability to make extra repayments without any fees.
How it works
The benefits of our Bridging Loan

Bridging period up to 12 months

Buy now, sell your old home later

Sell your current property at any time within the bridging period

Live in your old property until your new home settles
Need to know more? Here's the details
Free guides & reports
Create a property report
Get a list of the similar property sales in the area.
Get a list of properties currently on the market, similar to the one you are looking at.
Get an estimation of the value of the property.
Your guide to bridging loans
If you're buying a new home before selling your current one, our guide can help you understand how to manage the transition. It explains how bridging loans work, what to consider, and what the loan process entails.
Frequently asked questions
A Bridging Loan is a type of loan that helps you finance a new home purchase now, while you work to sell your old one within a ‘bridging’ period of up to 12 months, starting from when you settle your new property.
A bridging loan allows you to purchase a new owner-occupied property before selling your existing property. Your existing property, whether it has a home loan that is refinanced into the Bridging Loan or is provided as additional security if it is mortgage-free, is used together with your newly purchased property to support the loan.
During the bridging period of up to 12 months, monthly interest charges are capitalised to the loan balance. Once your existing property is sold, the sale proceeds are used to reduce your loan balance, and the remaining loan converts to a standard variable home loan secured by your new property
Yes. You can apply for a pre-approval on your Bridging Loan.
Our Bridging Loan is available to customers who are selling their existing owner occupied or investment property, to purchase a new owner occupied property. The new purchase must be owner occupied.
Yes. Interest will be calculated and charged on your loan throughout the bridging period of up to 12 months. During this time, the monthly interest charges are capitalised to your loan balance, which means interest added to your loan limit owing rather than being paid separately via a monthly repayment. As a result, you won't need to make repayments during the bridging period, and the amount of interest charged will be included in your outstanding loan balance.
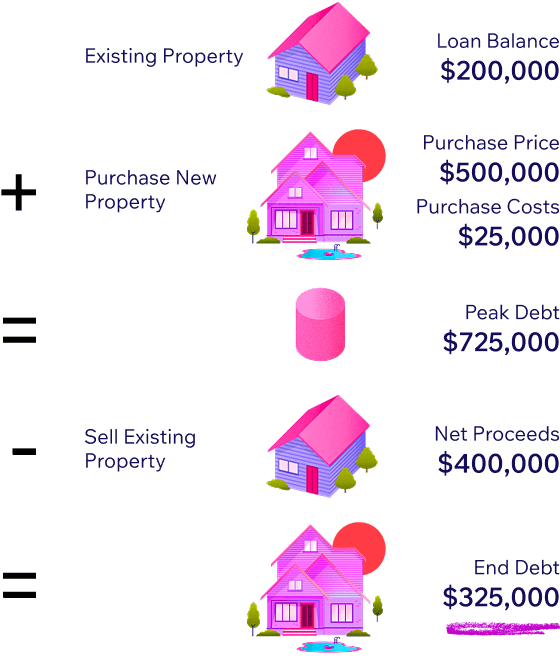
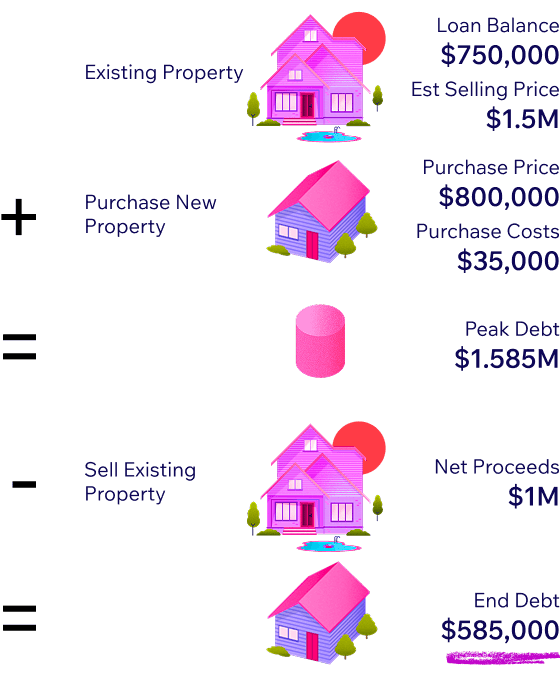
Peak debt is the total you owe at the highest point: your existing home loan balance (if any), plus the purchase price of your new property, plus any costs you’ve added to the loan such as stamp duty and legal fees.
End debt is what remains after your current home sells, and the proceeds are applied. This becomes your ongoing home loan. If you’re downsizing, your sale proceeds may cover the balance in full, in which case there is no end debt at all.
If you sell your existing property before the end of the bridging period, the sale proceeds will be used to reduce your loan balance (the peak debt). Once the sale has settled and your peak debt is reduced with the proceeds, your Bridging Loan will convert to a standard variable home loan secured by your new property only. You'll then begin making repayments on the remaining loan balance in accordance with your loan contract. There are no fees for completing your bridging period prior to the maximum 12 months allowed.
When your current home sells, the proceeds are applied to your balance. What’s left is your end debt, which becomes a standard variable home loan with us.
From that point you’ll have access to your home loan through our Smart Money app where you'll make normal principal and interest repayments on the remaining balance.
If your sale proceeds cover the balance in full, the loan is closed out and there’s nothing further owing.
Our bridging loan application process

Speak to our Specialist
Make an appointment with our lending specialists who will guide you through the bridging loan process, including getting a pre-approval tailored to your needs.

Upload & Track
Submit your documents and monitor your application in real time via our onTrack portal.

Approval & Signing
Review and sign your mortgage documents and loan agreement via onTrack.

Settlement
Your loan settles, which means your funds will be ready.

Manage Your Loan
You'll receive your login details to manage your repayments and account details via our Smart Money app.
Customer reviews

Our Google Rating


Refer your friends or family to loans.com.au and earn big rewards!
When they settle a home loan with us, you'll both receive a $1,000 reward. Plus, if they choose a car loan, you'll get a $250 bonus, and they'll enjoy $150 off their settlement fee. It's our way of saying thanks for spreading the word!+
+ T&Cs apply, view here
Mary-Anne

Difference between conveyancer and solicitor
Solicitors and conveyancers can both do conveyancing work, but what's the difference between these two professions? Find out here.

What does subject to finance mean
If you have found a property and are ready to buy, you need to get your finances approved by a lender.
Pre-Qualify for a Home Loan: What You Need to Know
If you’re buying a home for the first time but don’t know where to start, getting pre-qualified for a home loan can be a good jumping off point.
What is land tax and who pays it?

How to research a neighbourhood before you buy
Different Types of Home Loans & How to Choose the Right One
You may also be interested in
Kathryn
Lending Specialist
Have questions?Talk to one of our lending specialists
As an experienced lending specialist, Kathryn and our team can answer all your questions to get you on track and start saving thousands.